LoanBaazar helps you explore loan and credit options from banks and NBFCs. Compare eligibility, fees and repayment terms before applying. Approval and pricing are determined by the lender.
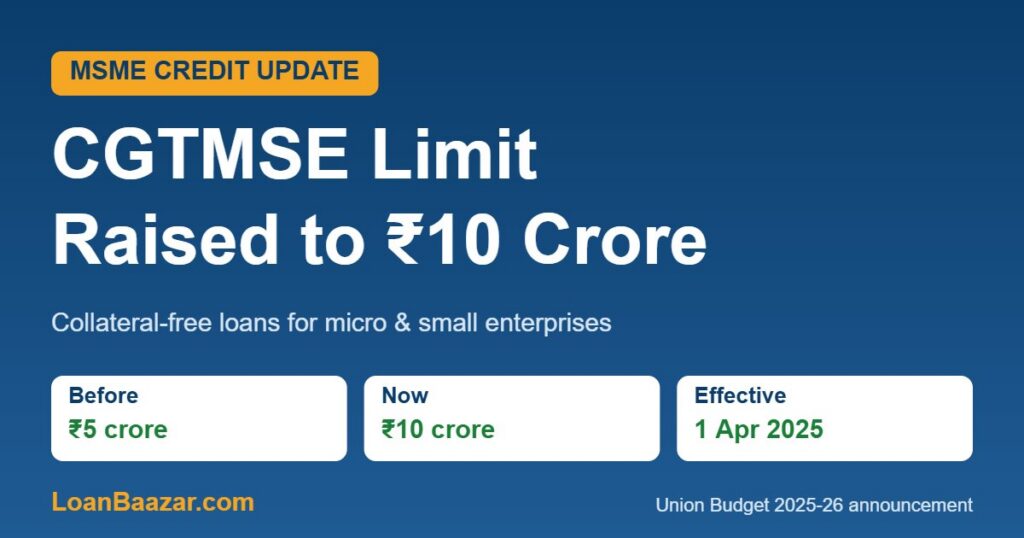
The CGTMSE limit for collateral-free loans to micro and small enterprises is now ₹10 crore, double the earlier ₹5 crore. Announced in the Union Budget 2025-26 and in force since 1 April 2025, the higher CGTMSE limit means an eligible MSME can borrow up to ₹10 crore from a bank or eligible NBFC without pledging property or giving a third-party guarantee. Here is what changed, who qualifies, what it costs and how to apply in 2026.
Last updated: 3 November 2026
Key Highlights
- CGTMSE guarantee ceiling raised from ₹5 crore to ₹10 crore per eligible borrower, effective 1 April 2025.
- The government expects the change to add about ₹1.5 lakh crore of extra MSME credit over five years.
- Guarantee fee was moderated to 1% for loans in 27 focus sectors linked to Aatmanirbhar Bharat.
- Credit guarantee cover for startups was raised from ₹10 crore to ₹20 crore in the same Budget.
- You apply through your bank or NBFC, not directly to CGTMSE; Udyam registration is required.
Table of Contents
- What changed in the CGTMSE limit
- How CGTMSE works
- Who is eligible
- Guarantee coverage and fees
- What the ₹10 crore CGTMSE limit means for your business
- How to apply
- FAQs
What Changed in the CGTMSE Limit?
In her Budget speech on 1 February 2025, Finance Minister Nirmala Sitharaman announced a package of credit measures for MSMEs. The changes relevant to borrowers:
| Measure | Before | From 1 April 2025 |
|---|---|---|
| CGTMSE guarantee cover for micro and small enterprises | Up to ₹5 crore | Up to ₹10 crore |
| Guarantee fee for loans in 27 focus sectors | Standard rates | Moderated to 1% |
| Credit guarantee cover for startups | Up to ₹10 crore | Up to ₹20 crore |
| MSME classification limits | Lower thresholds | Investment limits raised 2.5x, turnover limits 2x |
Because the MSME classification thresholds were raised at the same time, many businesses that were previously “medium” now count as micro or small enterprises, and can use CGTMSE for the first time.
How CGTMSE Works
The Credit Guarantee Fund Trust for Micro and Small Enterprises (CGTMSE) was set up by the Ministry of MSME and SIDBI. It does not lend money itself. Instead, it guarantees a large share of a loan given by a Member Lending Institution (MLI), such as a bank, small finance bank or eligible NBFC. If the borrower defaults, CGTMSE pays the lender the guaranteed share. This lets the lender sanction loans without collateral.
- Covered loans: term loans and working capital, or both, for new and existing units.
- Not required: property mortgage or third-party guarantee for the guaranteed amount.
- Above ₹10 crore: lenders may use a hybrid model, with the first ₹10 crore under CGTMSE and the balance against partial collateral.
Who Is Eligible for the ₹10 Crore CGTMSE Limit?
| Criterion | Requirement |
|---|---|
| Type of enterprise | Micro or small enterprise in manufacturing, services or eligible trading activity |
| Registration | Valid Udyam registration |
| Lender | A CGTMSE Member Lending Institution (most banks and many NBFCs) |
| Loan | Sanctioned without collateral or third-party guarantee (or under the hybrid model) |
| Excluded activities | Agriculture, self-help groups, educational institutions and other activities excluded by CGTMSE |
| Category | Investment up to | Turnover up to |
|---|---|---|
| Micro | ₹2.5 crore | ₹10 crore |
| Small | ₹25 crore | ₹100 crore |
CGTMSE Guarantee Coverage and Fees
CGTMSE typically guarantees 75% of the loan, rising to 85% for micro-enterprise loans up to ₹5 lakh and for priority categories such as women entrepreneurs, SC/ST borrowers and units in the North East and aspirational districts. The lender pays an Annual Guarantee Fee (AGF), which is usually passed on to the borrower.
| Loan amount | Annual guarantee fee (approx.) |
|---|---|
| Up to ₹10 lakh | 0.37% |
| ₹10 lakh – ₹50 lakh | 0.55% |
| ₹50 lakh – ₹1 crore | 0.60% |
| ₹1 crore – ₹2 crore | 0.85% |
| ₹2 crore – ₹5 crore | 1.00% |
| ₹5 crore – ₹10 crore | 1.10% – 1.20% |
Example: on a ₹1 crore CGTMSE loan, a 0.60% fee works out to about ₹60,000 a year, usually far cheaper than arranging property as collateral.
What the ₹10 Crore CGTMSE Limit Means for Your Business
- Bigger expansion without property: growing manufacturers and service firms can fund machinery, capacity and working capital up to ₹10 crore on cash-flow strength.
- Collateral freed up: promoters no longer need to pledge their homes for larger loans.
- More businesses qualify: the higher MSME thresholds bring many former medium units into the micro and small categories.
- Lower risk for lenders: the guarantee encourages banks to lend to first-generation entrepreneurs with good plans but few assets.
Smaller needs may be better served by Mudra (up to ₹20 lakh): see PM Mudra Yojana explained and our complete MSME loans guide.
How to Apply for a CGTMSE Loan up to ₹10 Crore
- Register on the Udyam portal if you have not already.
- Prepare a project report with funding need, cash-flow projections and repayment plan. See how to make a project report for bank loans.
- Approach a bank or eligible NBFC and ask for the loan to be covered under CGTMSE.
- Submit KYC, Udyam certificate, ITRs, financial statements and bank statements.
- After appraisal, the lender registers the loan with CGTMSE and pays the guarantee fee, then disburses.
Official scheme information is available on the CGTMSE website.
CGTMSE Limit FAQs
What is the CGTMSE limit now?
The CGTMSE limit is ₹10 crore per eligible micro or small enterprise, raised from ₹5 crore with effect from 1 April 2025.
Can I apply for a CGTMSE loan directly?
No. You apply to a bank or eligible NBFC that is a CGTMSE Member Lending Institution and request CGTMSE cover; the lender registers the guarantee.
Is collateral needed for a ₹10 crore CGTMSE loan?
No collateral or third-party guarantee is needed for the amount covered under CGTMSE. For loans above ₹10 crore, lenders may ask for partial collateral on the balance.
How much does the CGTMSE guarantee cost?
An annual guarantee fee of roughly 0.37% to 1.2% of the loan depending on the loan size, with discounts for women, SC/ST, North East and other categories. The fee is usually recovered from the borrower.
Are medium enterprises eligible for CGTMSE?
CGTMSE covers micro and small enterprises. However, the revised MSME limits from April 2025 mean many businesses that were medium earlier now qualify as small.
Can a new business get a CGTMSE loan?
Yes. Both new and existing micro and small enterprises are eligible, subject to the lender’s appraisal of the project.
Conclusion
The ₹10 crore CGTMSE limit is one of the biggest boosts to collateral-free MSME credit in years. If your business needs funds to expand, prepare a strong project report, keep your credit record clean and approach lenders for CGTMSE cover. Explore business loan options on LoanBaazar or apply online, and read our earlier introduction to CGTMSE.
Disclaimer: LoanBaazar is a loan marketplace. Scheme terms are as announced by the Government of India and CGTMSE and may change; approval, interest rates and fees are decided by the lender. Please verify current terms with your lender or the CGTMSE website.
Related post