LoanBaazar helps you explore loan and credit options from banks and NBFCs. Compare eligibility, fees and repayment terms before applying. Approval and pricing are determined by the lender.
Need funds to start or grow your business but don’t have property to pledge? A business loan without collateral is possible in India through government credit guarantee schemes such as CGTMSE and Mudra, and through unsecured business loans from banks and NBFCs. This guide explains each option, the limits, who is eligible and how to apply.
Last updated: 28 October 2026
Key Highlights
- CGTMSE guarantees collateral-free loans to micro and small enterprises up to ₹10 crore (raised from ₹5 crore from 1 April 2025).
- PM Mudra Yojana offers loans up to ₹20 lakh without collateral; Tarun Plus (₹10–20 lakh) is for borrowers who repaid an earlier Tarun loan.
- Udyam registration is the first step for most government-backed MSME loans.
- Unsecured business loans from banks and NBFCs are faster but usually cost more.
- Lenders still check your business vintage, turnover, GST/ITR records and credit score.
Table of Contents
- What is a business loan without collateral?
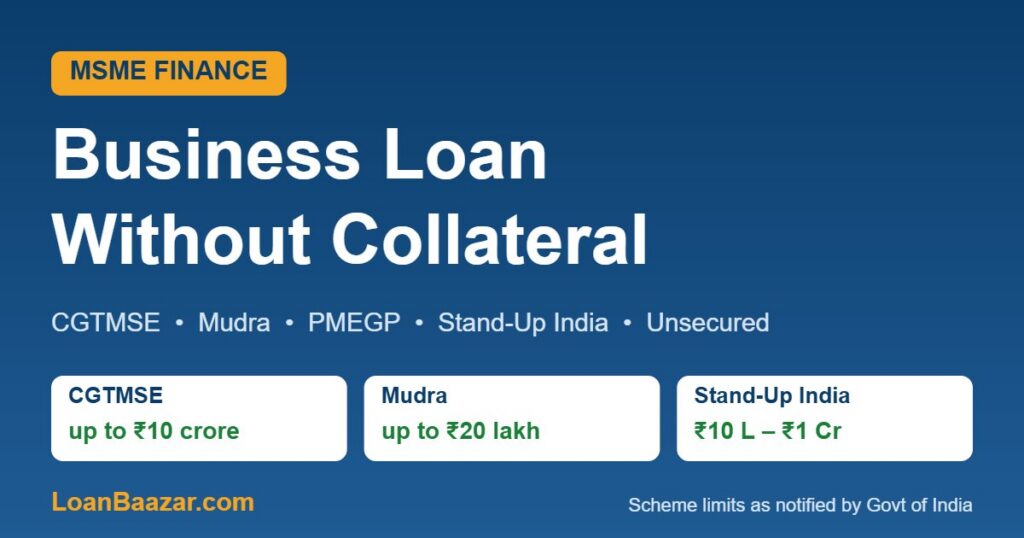
- Collateral-free business loan options in India
- CGTMSE: collateral-free loans up to ₹10 crore
- Mudra loan: up to ₹20 lakh
- Unsecured business loans from banks and NBFCs
- Eligibility and documents
- How to apply
- FAQs
What Is a Business Loan Without Collateral?
A business loan without collateral is a loan where you don’t pledge property, gold or fixed deposits as security. Instead, the lender relies on your business’s cash flows and credit record, and often on a government guarantee that covers a large part of its risk if the loan goes bad.
Collateral-Free Business Loan Options in India
| Option | Loan amount | Who it suits | Key point |
|---|---|---|---|
| CGTMSE-backed loan | Up to ₹10 crore | Udyam-registered micro and small enterprises | Government trust guarantees most of the loan; lender takes no collateral |
| PM Mudra Yojana (PMMY) | Up to ₹20 lakh | Micro and small non-farm businesses | Shishu, Kishor, Tarun and Tarun Plus categories |
| PMEGP | Project cost up to ₹50 lakh (manufacturing) / ₹20 lakh (services) | New micro enterprises | Bank loan with a government margin-money subsidy |
| Stand-Up India | ₹10 lakh – ₹1 crore | SC/ST and women entrepreneurs setting up a new enterprise | Composite loan for greenfield projects |
| Unsecured business loan (bank/NBFC) | Varies by lender | Businesses with steady turnover and good credit | Quick disbursal; higher interest rates |
CGTMSE: Collateral-Free Business Loans up to ₹10 Crore
The Credit Guarantee Fund Trust for Micro and Small Enterprises (CGTMSE) guarantees loans given by banks and eligible NBFCs to micro and small enterprises, so lenders can lend without collateral or third-party guarantees. From 1 April 2025 the guarantee ceiling was raised from ₹5 crore to ₹10 crore, and the annual guarantee fee was reduced. Both term loans and working capital qualify.
- Who can apply: new and existing micro and small enterprises in manufacturing, services and trading with Udyam registration.
- Cost: the lender’s interest rate plus an annual guarantee fee, which is often passed on to the borrower.
- Extra support: women-led units and units in identified credit-deficient districts get enhanced cover.
Read more in our CGTMSE scheme explainer.
Mudra Loan: Collateral-Free Business Loans up to ₹20 Lakh
Under the Pradhan Mantri Mudra Yojana, banks, NBFCs and MFIs give collateral-free loans to micro businesses, backed by the Credit Guarantee Fund for Micro Units (CGFMU). The maximum limit was doubled to ₹20 lakh in October 2024.
| Mudra category | Loan amount |
|---|---|
| Shishu | Up to ₹50,000 |
| Kishor | ₹50,001 to ₹5 lakh |
| Tarun | ₹5 lakh to ₹10 lakh |
| Tarun Plus | ₹10 lakh to ₹20 lakh (only for borrowers who have repaid an earlier Tarun loan) |
More details: PM Mudra Yojana explained and PMEGP scheme guide.
Unsecured Business Loans from Banks and NBFCs
Banks, NBFCs and fintech lenders also offer unsecured business loans based on your turnover, GST returns and banking history. They are usually approved faster and with less paperwork than scheme loans, but interest rates are higher and vary widely by lender and profile. Compare the total cost, including processing fees and foreclosure charges, before you sign.
Eligibility and Documents for a Business Loan Without Collateral
| Requirement | What lenders usually look for |
|---|---|
| Business registration | Udyam registration; GST registration where applicable |
| Business vintage | Existing businesses usually need a track record; Mudra, PMEGP and Stand-Up India also fund new units |
| Financials | ITRs, profit & loss statement and balance sheet (usually last 2 years for existing units) |
| Banking | Business bank statements for 6–12 months |
| Credit record | Healthy CIBIL score of the promoter and, if available, the business |
| Plan | Project report or business plan, especially for new units and larger loans |
A strong project report improves your chances: see how to make a project report for bank loans.
How to Apply for a Business Loan Without Collateral
- Register your business on the Udyam portal if you haven’t already.
- Choose the right route: Mudra for small needs up to ₹20 lakh, CGTMSE for larger MSE loans, PMEGP or Stand-Up India for a new unit.
- Prepare documents and a clear project report showing how the loan will be repaid.
- Apply to a bank or eligible NBFC, or online through the JanSamarth portal for government-linked schemes.
- Compare sanction letters on interest rate, fees and repayment terms before accepting.
Business Loan Without Collateral FAQs
Can I get a business loan without collateral in India?
Yes. Micro and small enterprises can get collateral-free loans backed by CGTMSE (up to ₹10 crore) or Mudra (up to ₹20 lakh). Banks and NBFCs also offer unsecured business loans based on turnover and credit history.
What is the maximum CGTMSE loan limit?
From 1 April 2025, CGTMSE guarantees loans to eligible micro and small enterprises up to ₹10 crore, up from ₹5 crore earlier.
What is the Mudra Tarun Plus limit?
Tarun Plus covers Mudra loans from ₹10 lakh to ₹20 lakh. It is available only to entrepreneurs who have taken and fully repaid an earlier loan under the Tarun category.
Is Udyam registration necessary for a collateral-free business loan?
For CGTMSE-backed and most government-scheme MSME loans, yes. It is free and done online on the Udyam portal.
Can a new business get a loan without collateral?
Yes. Mudra loans, PMEGP and Stand-Up India are designed to fund new enterprises, subject to the lender’s assessment of your project.
Why are unsecured business loan rates higher?
Without security or a government guarantee, the lender carries more risk, so it charges a higher interest rate. Scheme-backed loans are usually cheaper.
Conclusion
A business loan without collateral is within reach for most Indian MSMEs through CGTMSE, Mudra, PMEGP, Stand-Up India and unsecured lending. Start with Udyam registration and a solid project report, then compare offers. Explore business loan options on LoanBaazar or read our full MSME loans guide.
Disclaimer: LoanBaazar is a loan marketplace. Scheme limits are as notified by the Government of India; interest rates, fees and approval are decided by lenders. Please verify current terms with the lender or official scheme portal before applying.
Related post